GST on personal Health & Life insurance premium has been reduced from 18% to nil in September 2025. HR and other leaders should understand what’s changed and how it affects their employees. They should assess what these changes mean for their workplace benefits strategy, group insurance policies and overall employee experience.
GST on personal Health & Life insurance premium has been reduced from 18% to nil in September 2025. HR and other leaders should understand what’s changed and how it affects their employees. They should assess what these changes mean for their workplace benefits strategy, group insurance policies and overall employee experience.
On September 4, 2025, the 56th GST Council meeting introduced a major tax relief:
No GST on premiums for individual or personal health and term life insurance.
This move is part of the Indian government’s ongoing effort to simplify indirect taxes and make essential services like insurance more affordable for individuals and families.
So what does this mean for employers and HR teams? Let’s break it down.
What’s GST-Free Now: Individual Health & Life Insurance Plans
If you’re purchasing an individual or personal health insurance policy, you will now pay zero GST on the premium.
This includes:
Individual health insurance plans
Family floater policies
Health insurance for parents
Personal term life insurance
ULIPs ( Unit Linked Insurance Plan )
Example:
If your family floater policy previously cost ₹35,000 (including ₹5,338 in GST), it will now cost only ₹29662,000, the base premium. That's an instant saving of ₹5,338.
What HR Leaders Need to Know About the GST Changes
In 2026, the GST Council’s latest decision will help to reduce the effective cost of group health and group term life insurance for businesses. The Council has recommended allowing eligible businesses to claim Input Tax Credit (ITC) on GST paid for group health and life insurance.The GST rate on group insurance remains 18%, and the actual benefit will depend on the final legal provisions, eligibility conditions, and effective date.
What This Means for Corporate Benefits
Potentially lower insurance costs: Eligible businesses could offset GST paid on group insurance premiums against their eligible GST liabilities.
More flexibility in benefits planning: Employers could review their insurance budgets and consider improving coverage or adding benefits, depending on the savings available.
Greater access to employee insurance: Lower effective costs could make group insurance easier to afford for micro, small, and medium enterprises (MSMEs
Do You Need to Change Your Employee Benefits Strategy?
Not immediately. Employers should first confirm the applicable legal provisions, eligibility conditions, and implementation date, and work with their finance or tax teams to calculate the credit they can claim.
Group policies st offer better economics, superior coverage, and immediate protection even for parents. Refer to the table below to understand why:
Key Parameter
Group Policy for Parents
Retail Policy for Parents
Cost / Premium
Usually more economical due to bulk/group discount
Generally higher premium as it’s individually underwritten
Coverage Limit
Pre-defined by the group policy terms (may have a fixed sum insured)
Flexible – You can choose coverage limits based on your parents' needs
Policy Customization
Good options – Fixed terms as per corporate agreement
You have to customize based on age, health conditions, sum insured, etc.
Renewability
Generally guaranteed renewability up to a certain age (depends on the insurer)
May have restrictions on age of renewal or higher premium after a certain age
Additional Benefits
May include group-specific benefits (like wellness programs, corporate tie-ups, etc.)
No Add-ons available
Claim Settlement Ease
Group policies offer the benefit of corporate broker intervention, making claim settlement smoother.
Retail policyholders must directly deal with TPA & insurer, which may require more effort.
Key points:
Group health insurance premiums are still subject to 18% GST
Group term life insurance is not GST-exempt
Super Top-Up plans added by employees (especially for parents or dependents) also attract GST if purchased under group plans or through payroll
Your voluntary parental health insurance may see disruption - be prepared to educate employees
However, if employees buy individual Super Top-Up plans directly, those may qualify for the GST exemption
Why is Buying Super Top Up Still Better in Group Policy?
While the GST in taking individual Top-up will be exempted, effective discount in them will be near 5-8% only as insurers will lose on ITC from other operations. Buying top-up in a group policy ensures that you have coverage from 1st day rather than having a waiting period, As well as the premium is 5-10% cheaper than individual policy pre GST effectively landing you at the same cost with more accessible insurance partner like Pazcare.
Important Note: The way a plan is purchased (individually vs. under a group policy) affects GST applicability. HR teams should help clarify this for employees.
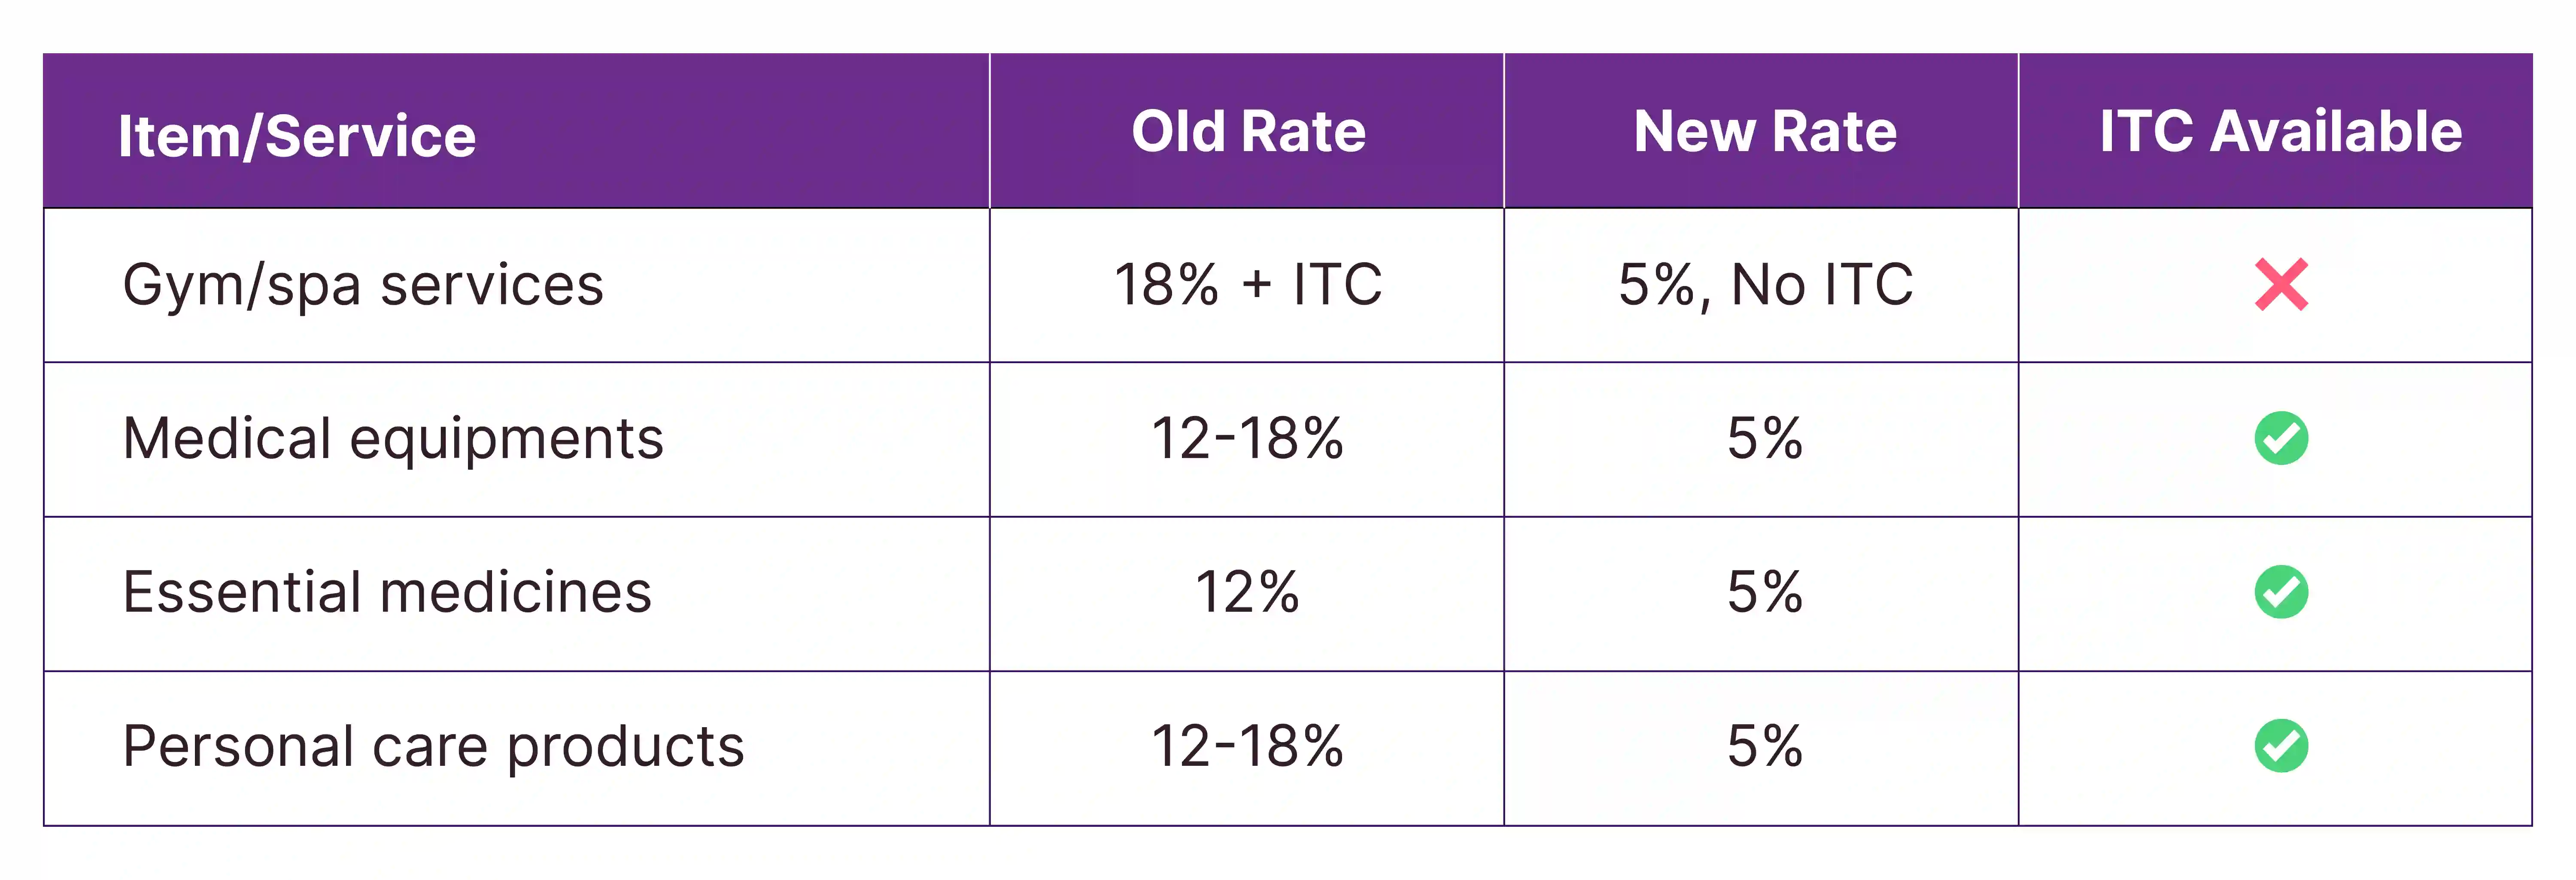
Wellness and Health Products: Mixed Changes
Some wellness programs (certified corporate fitness services) now attract only 5% GST instead of 18%
Medical equipment and essential medicines have expanded under the 5% GST slab
But not all personal care items qualify for reduced GST also fall under the 5% tax bracket which was earlier 12%-18%
What HR & People Teams Should Do Post-GST Change
For HR leaders and People & Culture teams, this update opens up opportunities to help employees make smarter insurance decisions.
Educate Employees about differences in retail and Group plans for dependents
With no GST, individual policies for parents or spouses are more affordable than ever.
Promote Super Top-Ups for higher coverage
Employees who want extra coverage beyond the company policy can still opt for Super Top-Ups even though GST may apply depending on how they’re purchased.
Offer personalized insurance advisory
Use Pazcare’s employee benefits platform to help your team compare plans and get the best value with or without GST.
Enhance wellness focus
With reduced GST on fitness services you can expand corporate wellness programs. Negotiate better rates with fitness partners and Promote preventive health initiatives in your organization.
Amar is the Finance Head at Pazcare, leading financial strategy for the insurance and employee benefits space since September 2024. A Chartered Accountant with expertise in FP&A, corporate finance, and tax management, he drives growth, cost efficiency, and revenue monitoring. His experience across startups, MNCs, and Big4 audits helps him deliver sharp financial insights tailored to the evolving benefits and insurance industry.
Follow on:
Thanks for subscribing! If it’s your first time, check your inbox. Otherwise, you’re already on our list
Oops! Something went wrong while submitting the form.
Ready to give yourself and your team the best employee benefit experience?