As a salaried employee, maximizing tax savings is crucial to maintaining financial stability and ensuring a comfortable future. By taking advantage of various tax-saving options, you can significantly reduce your tax liability and increase your disposable income.
Also check: Employee benefits in India
What changed from 1 April 2026
- A new Act. The Income-tax Act, 2025 replaces the Income-tax Act, 1961. Income up to 31 March 2026 (FY 2025-26) is still assessed under the old Act, so returns you file this year for FY 2025-26 still use the old section numbers.
- "Tax Year" replaces "Previous Year" and "Assessment Year". Income earned from 1 April 2026 to 31 March 2027 is simply Tax Year 2026-27.
- New forms. Form 16, the annual salary TDS certificate, is now Form 130.
- Higher limits for employer benefits. The Income-tax Rules 2026 raise the tax-free limits on meals, gifts, and food allowances.
In this article, we'll explore 10 effective tax-saving tips for salaried employees in 2026.
1. Invest in a Public Provident Fund (PPF):
Public Provident Fund (PPF) is a popular investment avenue in India that not only helps individuals build long-term savings but also provides tax benefits. Here's how investing in PPF can help public sector employees save taxes:
a. Investments made in PPF are eligible for a deduction under Section 80C of the Income Tax Act. Public sector employees can claim a deduction of up to Rs. 1.5 lakh in a financial year.
This deduction includes various other eligible investments and expenditures, such as life insurance premiums, ELSS (Equity Linked Savings Scheme), and more.
b. The interest earned on the PPF investment is tax-free. This means that the returns generated on the PPF investment are not added to the individual's taxable income. With a lock-in period of 15 years, employees looking for long-term savings with tax benefits.
c. PPF allows partial withdrawals from the 7th year onwards. Employees facing financial emergencies can make partial withdrawals without attracting any tax liability. Loans can also be availed against the PPF balance, providing a source of liquidity without any tax implications.
2. Utilize the Employee Provident Fund (EPF):
The Employees' Provident Fund (EPF) is a mandatory savings scheme for salaried individuals in India, and it primarily serves as a retirement corpus. While contributions to EPF are compulsory, there are tax benefits associated with it. Here's how you can save taxes using EPF:
a. Contributions made to EPF are eligible for a deduction under Section 80C of the Income Tax Act, up to a maximum limit of Rs. 1.5 lakh in a financial year. This deduction is part of the overall limit allowed for various eligible investments and expenditures.
b. The interest earned on EPF contributions is tax-free. This means that the returns generated on your EPF savings are not added to your taxable income.
c. EPF withdrawals after completion of 5 continuous years of service are tax-free. If you withdraw your EPF balance before completing 5 years, it becomes taxable in the year of withdrawal.
3. Consider National Pension Scheme (NPS):
The National Pension System (NPS) is a voluntary long-term retirement savings scheme that offers tax benefits to individuals in India. Here's how NPS can help employees save taxes:
a. Employees can claim deductions under Section 80CCD(1) for contributions to their NPS account, up to 10% of salary. An additional deduction of Rs. 50,000 is available under Section 80CCD(1B).
b. Partial withdrawals for specific purposes are allowed without tax implications. Annuity income is taxed based on the individual's income tax slab, with only the invested amount being taxable.
4. Maximize House Rent Allowance (HRA):
Employees residing in rented accommodations can claim a deduction on House Rent Allowance (HRA) under Section 10(13A) of the Income Tax Act.
a. The least of the following is deductible: actual HRA received, 50% of salary (for metro cities, 40% for non-metro cities), or excess of rent paid over 10% of salary.
b. To claim HRA deduction, employees need to submit rent receipts and a rental agreement with their employer as proof of the rented accommodation. The rent receipts should include details such as the amount paid, duration, landlord's name, and address.
Check out: HRA exemption calculator
5. Purchase Health Insurance:
a. Premiums paid for Health Insurance, including Super Top-Up plans, are eligible for a deduction under Section 80D. The total deduction limit depends on the age of the insured and parents.
b. The deduction is available for both regular Health Insurance plans and Super top-up health insurance plans, collectively.
6. Avail Home Loan Tax Benefits:
Paying home loans can offer tax benefits to employees in India through deductions available under the Income Tax Act. Here's how it can help save taxes:
a. The principal amount repaid towards the home loan is eligible for a deduction under Section 80C of the Income Tax Act. The maximum deduction allowed under this section is Rs. 1.5 lakh per financial year, which includes other eligible investments and expenditures.
b. The interest paid on the home loan is eligible for a deduction under Section 24 of the Income Tax Act. For a self-occupied property, the maximum deduction allowed is Rs. 2 lakh per financial year. For let-out or deemed let-out properties, there is no upper limit on the interest deduction.
c. If a home loan is taken jointly, all co-borrowers can individually claim deductions for both principal and interest repayments
7. Opting for Leave Travel Allowance (LTA):
LTA or Leave Travel Allowance is exempt from taxation under Section 10(5) of the Income Tax Act, subject to certain conditions.
a. The exemption is available for the actual travel expenses incurred on your leave, and it covers travel for yourself, your spouse, children, and dependent parents or siblings. To claim the LTA tax exemption, you must undertake travel within India.
b. LTA is not an annual exemption but is available in a block of four calendar years. The current block is between 2022-2025. If you don't claim LTA in a particular block, you can carry it forward to the first calendar year of the next block.
8. Opt for a Tax-Saving Fixed Deposit (FD):
a. The maximum deduction allowed under Section 80C is Rs. 1.5 lakh per financial year, and this limit includes other eligible investments and expenditures.
b. Tax-saving FDs come with a lock-in period of 5 years. The deposited amount cannot be withdrawn before the completion of this period.
c. Joint accounts can also be opened, but the tax benefit is available only to the primary account holder. The interest earned on regular fixed deposits is fully taxable, and the interest income is added to the individual's total income.
9. Opt for tax-free meal cards:
As per the Income Tax Act Section 17(2)(viii), meals provided to employees can be tax-free and this is called tax-free meal cards.
A standard allowance of Rs.200/meal is allowed by the government. If we consider the standard working days to be 22 and the standard working hours to be 8 - 10 hours per day, the employer can provide 2 meals a day. This means Rs. 200 per day So the amount allowed is Rs.8800/month and Rs.105,600 per annum. This is applicable as per the old tax regime.
10. Opt for the New Tax Regime:
If you have exhausted most of the deductions available under the old tax regime, you can switch to the new tax regime with lower tax rates. However, carefully evaluate the impact on your overall tax liability before making the switch.
How salaried employees should plan tax saving
Effective tax planning helps salaried employees reduce their tax liability while improving long-term financial stability. Instead of rushing to invest at the end of the financial year, employees should adopt a structured approach to tax planning that aligns with their income, financial goals, and the available deductions under the Income Tax Act, 1961.
Here are a few practical strategies salaried employees can follow:
1. Start investing early in the financial year
One of the most common mistakes employees make is waiting until the last quarter of the financial year to invest in tax-saving instruments. Starting early allows you to spread your investments throughout the year, manage cash flow better, and avoid rushed financial decisions. Early planning also enables you to choose investments that match both your tax-saving goals and long-term financial objectives.
2. Maximize the section 80C limit
Section 80C offers some of the most popular tax-saving opportunities for salaried individuals. Employees can claim deductions of up to ₹1.5 lakh per financial year by investing in eligible instruments such as the Public Provident Fund, Employees' Provident Fund, and Equity Linked Savings Scheme. Fully utilizing this limit can significantly reduce taxable income while building long-term savings.
3. Make use of employer-provided benefits
Many companies offer tax-efficient components within the employee’s compensation structure. Benefits such as House Rent Allowance (HRA), Leave Travel Allowance (LTA), meal allowances, and health insurance premiums can provide tax exemptions when claimed correctly. By understanding and utilizing these benefits, employees can increase their take-home salary while remaining compliant with tax regulations.
4. Compare the old and new tax regimes carefully
Before filing taxes, salaried employees should evaluate whether the old tax regime or the new tax regime offers greater benefits based on their income and deductions. The old regime allows several deductions and exemptions, while the new regime offers lower tax rates but limits most deductions. Comparing both options ensures that employees choose the regime that results in the lowest tax liability.
By following these tax planning strategies, salaried employees can make smarter financial decisions, reduce their tax burden, and build a more secure financial future. Proper planning not only improves immediate tax savings but also supports long-term wealth creation.
New Tax Regime Slabs (FY 2025–26)
| Income |
Tax Rate |
| Up to ₹4 lakh |
Nil |
| ₹4–8 lakh |
5% |
| ₹8–12 lakh |
10% |
| ₹12–16 lakh |
15% |
| ₹16–20 lakh |
20% |
| ₹20–24 lakh |
25% |
| Above ₹24 lakh |
30% |
Conclusion
By utilizing these 10 tax-saving options, salaried employees can optimize their tax planning and minimize their tax burden in 2026. Remember to consult a tax expert or financial advisor to assess your specific situation and make informed decisions. Start early, plan wisely, and secure a better financial future for yourself and your loved ones.
Tax-saving employee benefits solutions from Pazcare
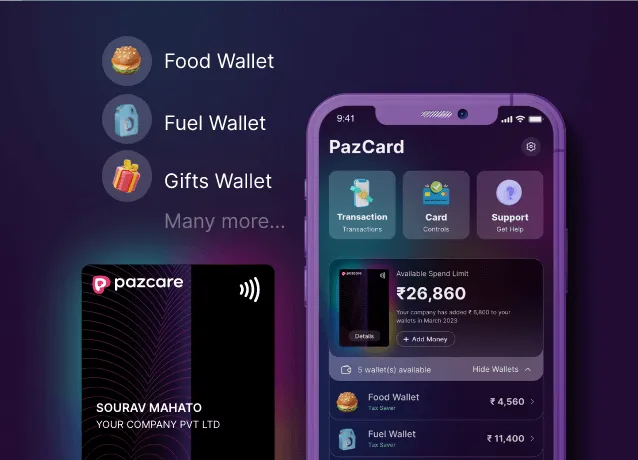
The Indian Government has allowed a few components like LTA, food allowance, fuel allowance, books and periodicals allowance, etc as part of your CTC. As employees, you can claim tax-free benefits on the same.
Pazcare offers these tax-free employee benefits solutions in a unique way. As employers, you can opt for this “Pazcard” benefit to maximize your employee’s take-home salary. Pazcare will create a Pazcard dashboard and activate wallets for individual employees requested. The employees can activate this wallet by completing the KYC process and start saving on taxes.